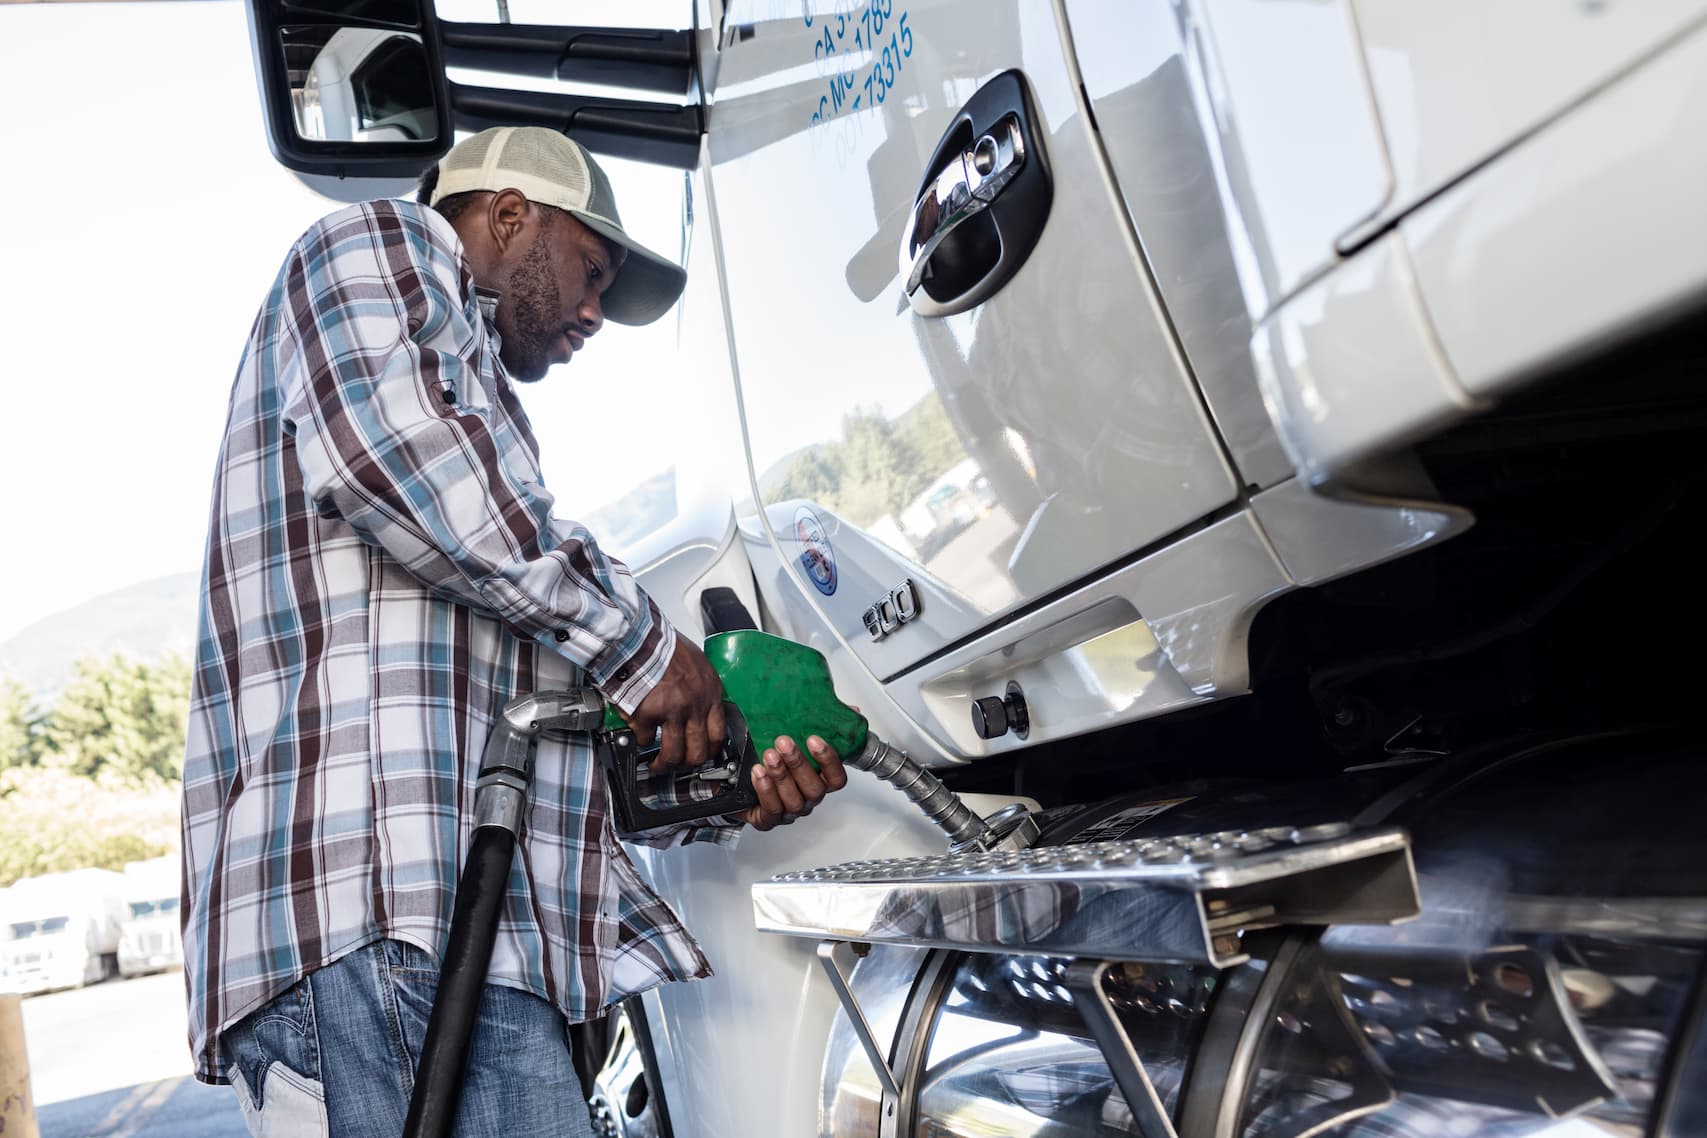
Diesel fuel prices rose 24.1 percent in a single month. That is not a crude oil story, and treating it as one leads to the wrong planning assumption. The diesel price surge is a refining and inventory problem, which is why it has outpaced crude.
What the August Data Showed
The Bureau of Labor Statistics reported that the Producer Price Index for final demand rose 0.4 percent in August and 5.4 percent over 12 months. Final demand goods advanced 1.1 percent after two consecutive decreases. Notably, over three fourths of that increase traced to energy, and prices for diesel fuel jumped 24.1 percent.
| Measure | Figure |
|---|---|
| Diesel fuel, August PPI | Up 24.1 percent |
| Final demand energy, August | Up 4.2 percent |
| Retail diesel, week ending Sept. 21 | $6.529 per gallon |
| Stage 1 intermediate demand, 12 month | Up 11.3 percent |
| Operable U.S. refineries, start of 2026 | 130 |
Retail prices confirm the direction. The Energy Information Administration put the national average on-highway diesel price at $6.529 per gallon for the week ending September 21st. Similarly, AAA recorded a record $6.51 on the same day.
Why This Is a Refining Story
Diesel and gasoline come out of the same barrel, but they do not come out in whatever ratio the market wants. A refinery has a physical yield range, so meeting a distillate shortfall means running harder rather than switching product mix at will.
That matters because the United States entered 2026 with 130 operable refineries. Moreover, the newest large full-service refinery in the country, Marathon’s Garyville facility in Louisiana, began operating in 1977. Consequently, when distillate demand runs ahead of supply, there is no idle capacity to bring online.
Inventories tell the same story. Distillate stocks fell to roughly 103 million barrels by late August, the lowest level for that point in the calendar since 1951. Furthermore, the EIA expects distillate inventories to stay below the five-year low through the end of 2026 and most of 2027.
The Supply Shocks Behind the Number
Several pressures arrived at once, which is why the move was so abrupt.
Russia banned diesel exports on July 9th, 2026. Because Russia had been the world’s second largest diesel exporter, that removed a substantial volume from the global pool. As a result, U.S. diesel exports hit a record high as buyers elsewhere sought replacement barrels. In other words, American refiners are supplying a tighter world market from the same constrained base.
Meanwhile, conflict involving Iran disrupted shipping near the Strait of Hormuz and Bab al-Mandab, and attacks hit Saudi Arabia’s East-West pipeline. A tanker shortage compounded it. The Institute for Supply Management cited petroleum based products among the drivers keeping its Prices Index elevated, alongside steel and aluminum prices and tariffs.
How It Reaches a Manufacturer
Very few manufacturers buy diesel as a primary input. Nearly all of them buy it indirectly, which is where the diesel price surge becomes a cost problem rather than a headline.
Freight is the main channel. Carriers respond to fuel costs with surcharges and rate increases. Therefore a plant with no diesel line item still pays the difference on every inbound and outbound load. Dry van spot rates recently averaged $2.77 per mile, up 43 percent against the same week in 2025.
The second channel is upstream pricing. Stage 1 intermediate demand measures what producers pay for the inputs they consume. In August it rose 1.4 percent, and 11.3 percent over the year. That is roughly double the rate of final demand, so input costs are climbing faster than the prices most manufacturers can charge. We covered the demand side of that squeeze in our look at core capital goods orders.
What to Do With This
Treating the diesel price surge as a temporary energy spike produces a wait-and-see response. The inventory and refining picture argues against that, because neither condition resolves on a quarterly timeline. Building a new full-service refinery is a multi-year project that nobody has completed at scale in decades.
Therefore the practical moves are contractual rather than operational. Review how fuel surcharges are calculated in carrier agreements. Notably, index-based surcharges reprice automatically while negotiated flat rates do not. Check whether long-term customer contracts contain any input cost adjustment mechanism. Above all, model landed cost rather than unit cost when quoting work into 2027.
Frequently Asked Questions
Why did diesel prices rise 24.1 percent in August 2026?
In short, the increase reflects a distillate supply shortfall rather than a crude oil price spike. Russia banned diesel exports in July 2026, and conflict disrupted shipping near the Strait of Hormuz and Bab al-Mandab. Meanwhile, U.S. refineries were already running near capacity with no spare output available.
How high are diesel prices now?
The Energy Information Administration put the national average on-highway diesel price at $6.529 per gallon for the week ending September 21st, 2026. AAA recorded a record $6.51 on the same date.
Why can’t refineries just make more diesel?
A refinery produces diesel and gasoline from the same barrel within a physical yield range. Consequently, it cannot freely shift product mix toward distillate. In addition, the United States had 130 operable refineries entering 2026, and the newest large full-service refinery began operating in 1977, so there is little idle capacity available.
How low are diesel inventories?
Distillate stocks fell to roughly 103 million barrels by late August, the lowest level for that point in the calendar since 1951. In addition, the EIA expects inventories to remain below the five-year low through the end of 2026 and most of 2027.
How does the diesel price surge affect manufacturers that do not buy fuel?
In practice, it arrives through freight. Carriers pass higher fuel costs through as surcharges and rate increases, so inbound and outbound transportation costs rise even for plants with no direct fuel purchases. Dry van spot rates recently averaged $2.77 per mile, 43 percent above the same week in 2025.
What is stage 1 intermediate demand?
Stage 1 intermediate demand is a Producer Price Index measure of what producers pay for the inputs they consume, rather than what buyers pay at the end of the chain. It rose 11.3 percent over the 12 months ending in August, roughly double the final demand rate.
The Bottom Line
The August number is not noise, and it is not really about oil. A distillate market this tight, supplied by a refining base this old, does not correct because a quarter ends. Consequently the firms that fare best will be the ones that repriced freight and revisited contract language before the fourth quarter, rather than after it. For more, see the full IndustrialSage Headlines Ep. 33 or our manufacturing and industrial news section.

Author: Wes Garrett
Content and Growth Marketing Producer | From Strategy to Execution, Delivering Impactful Media Solutions and Client Success