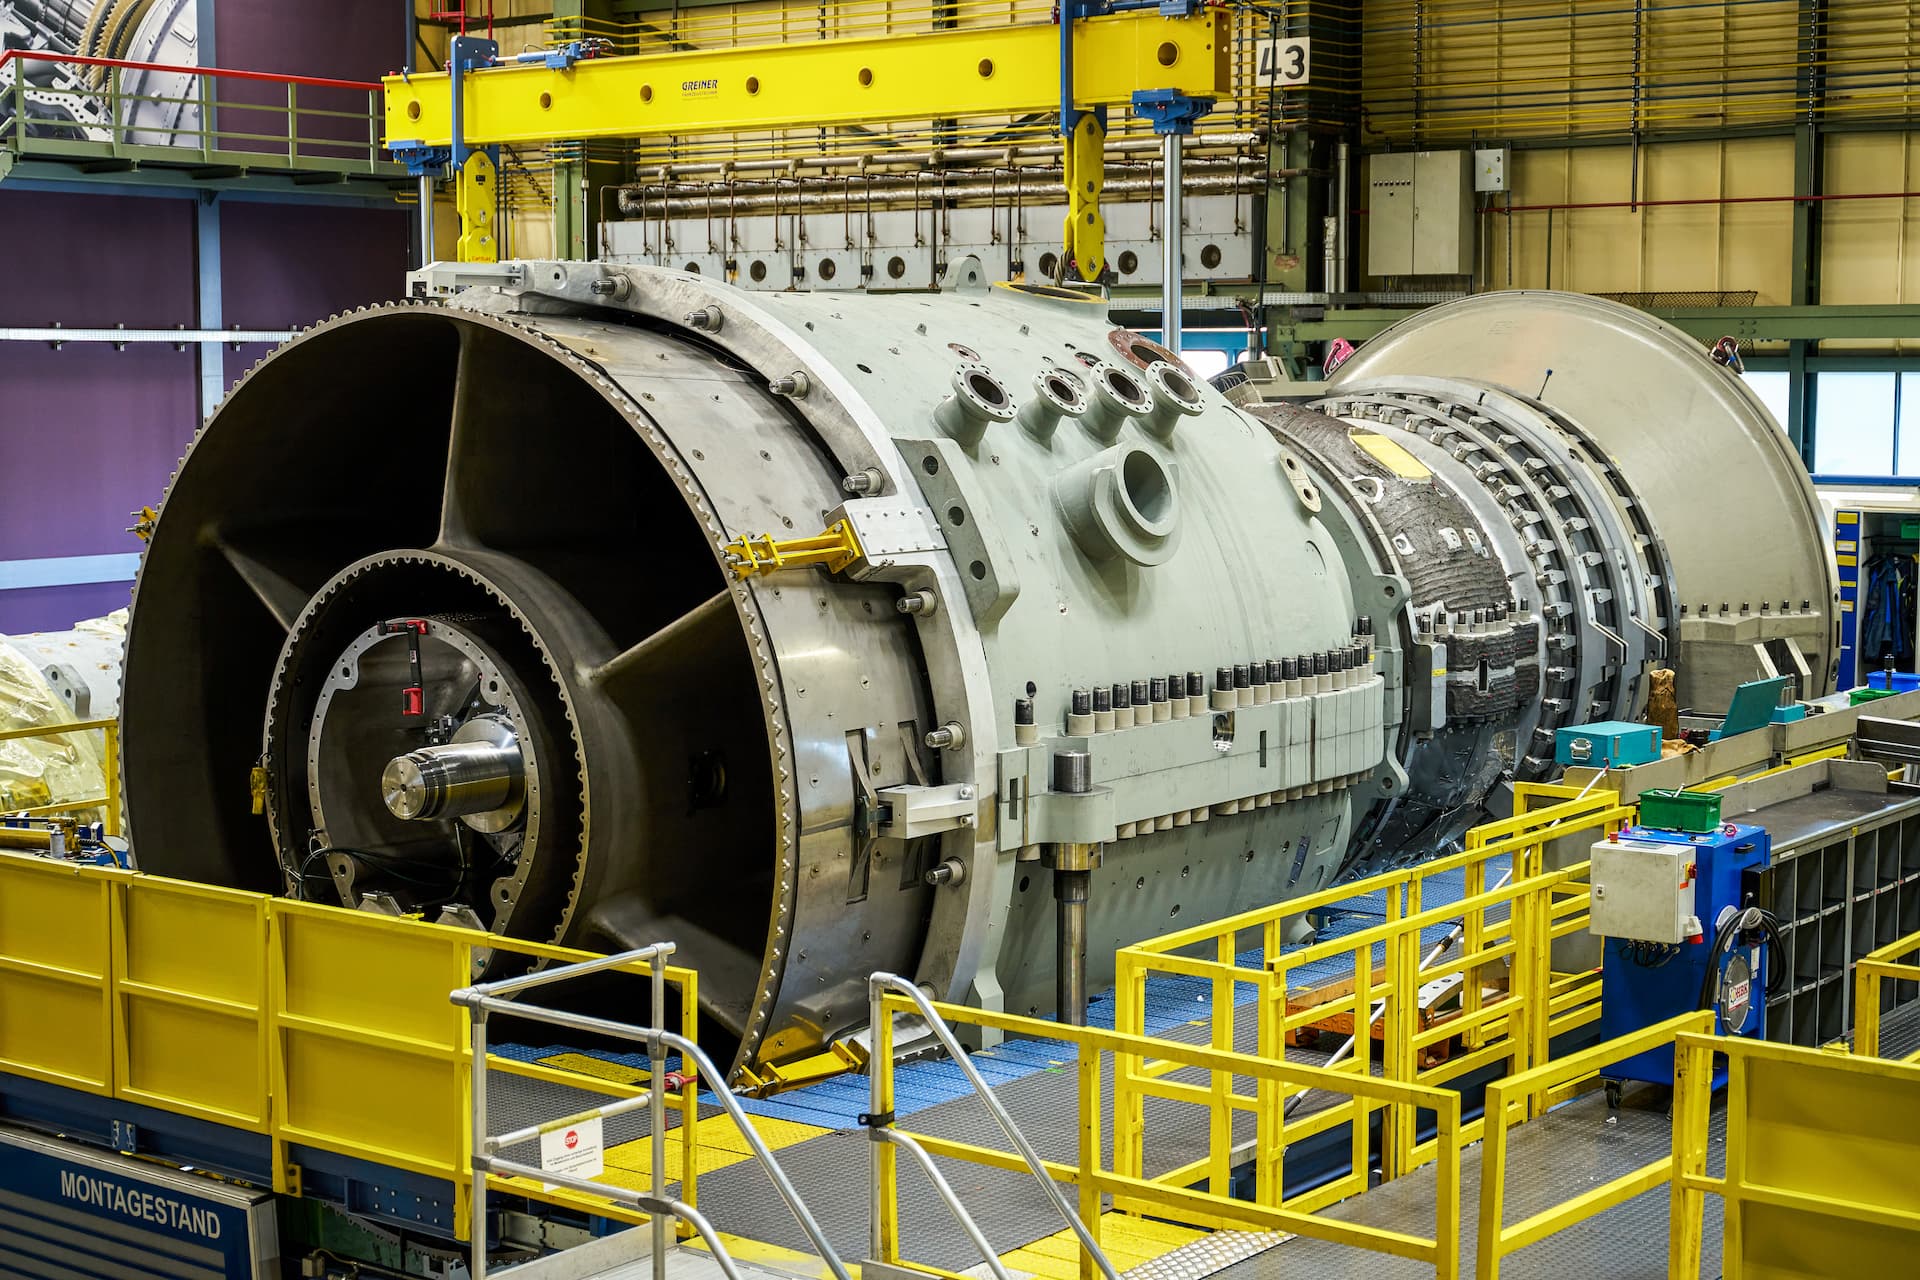
Gas turbine manufacturing capacity has become the binding constraint on America’s AI data center buildout. Indeed, neither capital nor demand is the limit. In fact, the clearest evidence turned up in an unlikely dataset. Power generation and distribution manufacturers outspent the entire automotive sector on factory machinery in the first half of 2026.
Key Takeaways
- Power generation and distribution manufacturers outspent automotive on machine tools by 14 percent in the first half of 2026, per AMT.
- U.S. manufacturing technology orders totaled $3.44 billion in the first half, up 36.0 percent year over year. Notably, that is the strongest half-year since USMTO tracking began in 1998.
- June 2026 orders alone reached $672.7 million. Moreover, that is up 15.6 percent from May and 56.8 percent from June 2025.
- Unit volume actually fell 2.6 percent, so buyers are adding automation content rather than simply adding machines.
- GE Vernova’s gas turbine backlog hit 116 GW in the second quarter of 2026, up from 100 GW. Meanwhile, annual output runs at roughly 20 GW.
- The company is now taking reservations for 2031 delivery and books current orders four to five years out.
- Siemens Energy committed $1 billion and 1,500 jobs to expand U.S. turbine and grid production. Specifically, that includes resuming turbine manufacturing in Charlotte.
- Gas turbine manufacturing capacity is constrained by large castings and forgings, which come from a very limited global supplier base.
Power Generation Outspent Automotive on Machine Tools
New orders of metalworking machinery totaled $672.7 million in June 2026, according to the U.S. Manufacturing Technology Orders report from AMT. Orders rose 15.6 percent from May and 56.8 percent from June 2025. Consequently, the first half closed at $3.44 billion, a 36.0 percent gain over the same period in 2025. Furthermore, that is the strongest half-year since collection began in 1998.
However, the headline figure is not the interesting part. Rather, the interesting part is who was buying. Makers of engines, turbines and power transmission equipment accelerated their orders to serve electricity demand created by new AI infrastructure. As a result, power generation and distribution manufacturers outspent the automotive sector by 14 percent.
For an industry that has treated automotive as its bellwether customer for decades, that is a genuine reordering. Notably, capital equipment decisions typically get made twelve to eighteen months ahead of delivery. These orders were therefore committed while tariff uncertainty still dominated trade coverage, and manufacturers kept buying anyway.
GE Vernova’s Backlog Now Runs Five Years Deep
Clearly, the demand side explains why. GE Vernova ended the second quarter of 2026 with a gas turbine backlog of 116 GW. By comparison, in the first quarter it stood at 100 GW. Against roughly 20 GW of annual output, that backlog represents about five years of production already committed.
Furthermore, the company expects at least 125 GW under contract or reserved by the end of 2026. It is currently taking reservations for 2031 delivery. In addition, it anticipates being more than halfway contracted for that year before 2026 closes. Current orders book four to five years out.
| Metric | Figure |
|---|---|
| Gas turbine backlog, Q2 2026 | 116 GW |
| Gas turbine backlog, Q1 2026 | 100 GW |
| Current annual output | Roughly 20 GW |
| Planned annual output by 2030 | 30 GW |
| Expected backlog plus reservations, end 2026 | At least 125 GW |
| Reservations now open for | 2031 delivery |
| Data center share of backlog | About 20 percent |
Data centers account for only about 20 percent of that backlog. Traditional utilities hold the remaining 80 percent across roughly 100 customers in 26 countries. In other words, AI is not the whole story. Rather, AI demand arrived on top of utility demand that already existed, and the combination overwhelmed the factories.
Why Gas Turbine Manufacturing Capacity Cannot Scale Quickly
Naturally, turbine plants cannot simply add a shift. The tightest bottleneck sits in large castings and forgings, including blades and rotors. According to Siemens Energy, those parts come from a very limited global supplier base. These parts demand precision investment casting, specialized heat treatment and testing regimes that take years to qualify.
Because of that, turbines ordered now may not ship until 2029 or later. Reporting from Power Engineering and Utility Dive puts the wait for a large gas turbine as high as seven years. Before the surge, that wait ran roughly two and a half to three years. Manufacturers who want to widen that pipe have to buy machine tools first. In short, that is exactly what the USMTO data captured.
In practice, this pattern should look familiar. IndustrialSage documented the same dynamic in grid hardware. There, power transformer lead times reached 128 weeks and prices climbed 77 percent since 2019. Ultimately, turbines are the same story with a longer fuse.
Siemens Energy’s $1 Billion Bet on US Turbine Production
On February 3, 2026, Siemens Energy committed $1 billion and more than 1,500 jobs. Specifically, the money expands U.S. grid and turbine production. Significantly, the plan resumes gas turbine manufacturing in Charlotte, North Carolina. The company built turbines there from 2011 until shutting the line in 2020.
Siemens Energy has been making things in the United States for more than a century and we are experiencing a once-in-a-generation growth opportunity due to the resurgence of U.S. manufacturing and the growth of artificial intelligence.
Christian Bruch, CEO and President, Siemens Energy
| Location | Scope |
|---|---|
| Charlotte, North Carolina | Resumes gas turbine manufacturing, expands transformers |
| Winston-Salem, North Carolina | Gas turbine parts |
| Tampa, Florida | Blades and vanes for gas turbines |
| Greater Richland, Mississippi | New high-voltage switchgear plant, up to 300 jobs |
| Fort Payne, Alabama | Generator components, 120 jobs |
| Painted Post, New York and Houston, Texas | Compression equipment upgrades |
Importantly, Tampa matters more than its line item suggests. Blades and vanes are precisely the hot-section parts that gate everything else. Therefore, adding that capacity attacks the actual bottleneck rather than final assembly. Even so, the Charlotte line is not expected to ship turbines for another two to three years.
What Gas Turbine Manufacturing Capacity Means for Suppliers
For machine shops, tooling houses and automation integrators, this is the clearest demand signal in the market. Power equipment makers have committed to multi-year capacity expansions. However, they cannot execute without precision machining, large-part handling and inspection capability. Therefore the work is durable rather than cyclical.
Consequently, three implications follow. First, capability in large castings, forgings and hot-section machining is worth more than generic capacity right now. Second, buyers are specifying automation content aggressively. As a result, integrators who deliver robotic load and unload and integrated vision have pricing power. Third, gas turbine manufacturing capacity constraints will persist through at least 2028, because even announced expansions do not land sooner.
Manufacturers tracking where this capital lands can follow announced commitments on our US Manufacturing Investment Tracker. For ongoing coverage, visit our manufacturing and industrial news section or watch the full breakdown in IndustrialSage Headlines Episode 31.
Frequently Asked Questions
Why is gas turbine manufacturing capacity limiting AI data centers?
Demand for gas turbines has outrun the factories that build them. GE Vernova ended the second quarter of 2026 with a 116 GW backlog against roughly 20 GW of annual output. Therefore the constraint is factory throughput rather than orders.
How long is the wait for a new gas turbine?
GE Vernova books current orders four to five years out and is taking reservations for 2031 delivery. Reporting from Utility Dive and Power Engineering puts the wait as high as seven years. Before the demand surge, it ran roughly two and a half to three years.
How large is GE Vernova’s gas turbine backlog?
The backlog reached 116 GW at the end of the second quarter of 2026, up from 100 GW in the first quarter. The company expects at least 125 GW of gas equipment under contract or reserved by the end of 2026.
Why did power generation outspend automotive on machine tools?
Makers of engines, turbines and power transmission equipment accelerated capital equipment orders to expand capacity. AMT reported that orders from power generation and distribution manufacturers ran 14 percent above automotive sector investment in the first half of 2026.
What part of a gas turbine is hardest to manufacture?
Large castings and forgings, particularly blades and rotors, come from a very limited global supplier base, according to Siemens Energy. Those components require precision investment casting and specialized heat treatment, which is why adding capacity takes years rather than months.
What is Siemens Energy doing to add US turbine capacity?
Siemens Energy committed $1 billion and more than 1,500 jobs across seven states on February 3, 2026. The plan resumes gas turbine manufacturing in Charlotte, North Carolina. Additionally, it adds blade and vane production in Tampa, Florida and a new high-voltage switchgear plant in Mississippi.
Did manufacturers order fewer machines in 2026?
Yes. Unit volume fell 2.6 percent against the second half of 2025 even as order value rose 36 percent. AMT attributes the gap to automation content specified onto each machine. Examples include robotic load and unload, pallet systems and integrated vision.

Author: Wes Garrett
Content and Growth Marketing Producer | From Strategy to Execution, Delivering Impactful Media Solutions and Client Success